

The cost of not going location independent – retirement problem!
For those with some savings and uncertain income, going location independent can be a great way to boost their quality of life.
But what’s the cost of staying in your home country if you already do have good income – the kind that you wouldn’t have to give up when moving abroad?
If you live in any western country, you can bet that your taxes are not low, and you shouldn’t underestimate the total amount. Most people think that they only pay a low double-digit percentage, when in reality they pay much, much more. The “hidden” taxes are a serious problem, one that I’ve written about in my blog post “What part of your life should be forced government labor?“. I hope that helps you consider the total costs, and to do your math carefully!
The thing that I hint at there, but don’t really dive into, is the problem of being able to retire. When you “work most of the year” for the government, that really wreaks havoc on any savings calculations. You have your own costs to cover, and when the government takes most of your money (not even going into how all those other taxes then push up the living costs!), you have very little left for savings and investment.
Those savings and investments are something that you will need for retirement. Sure, in most countries the government also forcibly confiscates some part of your income to “invest” into their pension schemes, but those schemes are often completely hare-brained. When you run the numbers, you can’t but walk away with the depressing conclusion that they seem much more like a pyramid scheme than a pension scheme.
That is definitely the case in Finland. You can at best expect to get crumbs, when compared with you keeping that money for yourself and investing it even in low-risk, low-return investments. Even those low returns compound over the years, but the government “investments” get siphoned elsewhere.
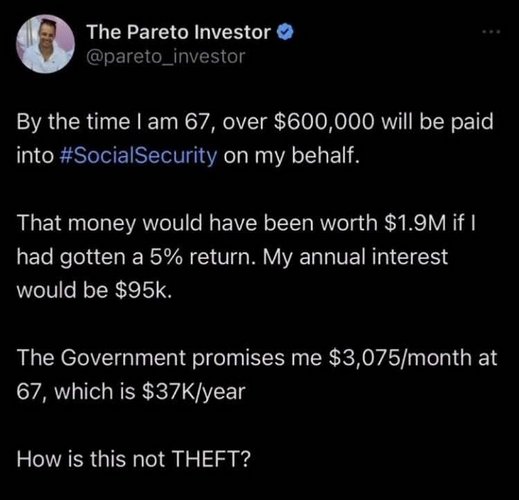
Finns can only dream of their bankrupt pension system stealing only that little!
That’s not just some innocent or accidental design “flaw”. The purpose of the system is what it does.
When you listen to the proponents of these system (politicians), it becomes very clear that the real design philosophy is that other people should have the right to make any decisions with their finances, whatever the result, and it is your duty (as a productive person) to nevertheless guarantee them a pension! Instead of being a good steward of your money, the system is engineered to funnel that money to other people in the name of “fairness”.
My problem with this system is two-fold:
1 – The pension system itself:
It’s been clear for decades that the system is, at best, built on “hopes and wishes” that the “economy would grow forever”, conveniently “forgetting” to take into account the shaky shape of the population age pyramid. Even in the early 2000s, I remember our friend group laughing at the idea of ever getting a pension. We weren’t exactly pension fund professionals, but even then it was blatantly obvious that the whole system was more or less a total scam.
Of course, the people responsible for this must have been conscious of what they’re doing: they’ve built a pyramid scheme, calculating that they themselves will have time to get out of the way before it collapses. The money the productive people of today have to pay into the system is overwhelmingly used just to keep the current payment obligations funded – for now. Only a tiny amount of today’s payments into the system are invested so the people currently funding the pyramid scheme could have any pension.
With the amount of money printing the governments will be forced to do (with mathematical certainty, in order to prevent full default), the purchasing power of these future pensions can be expected to be quite minimal. There are no scenarios (besides some sudden crazy sci-fi future through AI maybe?) where those pensions cover actual living costs. The current appreciation of the pension investments is nowhere enough to overpower future inflation, and the problem only keeps getting worse.
While I do – in a purely mathematical sense – understand that the more money that would be used to feed this pyramid scheme, the longer it could go on, I don’t think that translates into any kind of moral obligation to actually keep it going.
Any amount of money any individuals would be able to pour into this fraudulent machine doesn’t change the fact that it is still clearly a pyramid scheme. Participating in those always ends bad for everyone involved, and the sooner people realize these systems for what they are, the better – even if it means pain in the short term!
2 – The attitude of the tax-feeders in general:
My problem with this overall system of government-led anything is not about the current pensioners (who’ve just been fed the same lies as everyone else, and have, as individuals, acted in good faith).
If I were living permanently in these effectively-bankrupt legacy countries, the government would take away the overwhelming majority of the value I produce. Whether they would do that under the guise of “pension duties” or whatever name they give to these mandatory payments to government, at the end of the day it is all just the same: taxation. It is money you pay to the government, whether you like it or not, and you will never see that money again. It is funneled directly to others, with the ever-sorrier excuse of “fairness”.
Personally, even if I could somehow ignore these “lifetime millions” being stolen from me, the real issue isn’t money. The bigger problem is the attitude of the people on the receiving end of this money.
The more you “contribute” to people who loudly demand for more of your money, the more they seem to hate you – and as a consequence, the more they vote for that money to be used against you.
This is why my reluctance to live in these countries isn’t about money per se, but about principle: if I’m clearly not wanted, why would I force myself upon these countries? If people in other countries are either happy to receive me, or at least indifferent to my existence there, isn’t it better for everyone if I go to those places instead?
What you are, should be, and shouldn’t be responsible for
I want to make it clear that I do not advocate for any delusional notion that everyone should be 100% responsible only for themselves. The idea that the financial top 20% of the society should participate in helping the bottom 20% along is not unreasonable at all. That’s how any human society ever has always worked! We know that not everyone is that smart or great with money, and sometimes people can just have really bad luck and not be able to finance their living at old age. It is actually, truly fair to help them!
None of that is a problem, nor has it ever been a problem.
Our current problem is quite different.